
myEquifax
- Rating
- 4.6
- Downloads
- 500.00K
- Content Rating
- Everyone
myEquifax - Screenshots
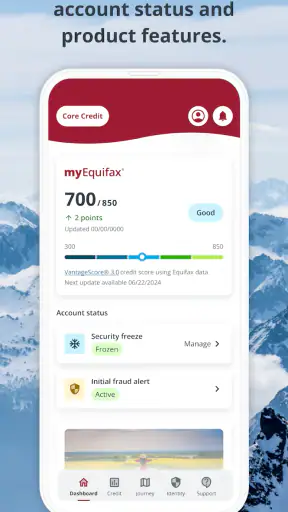
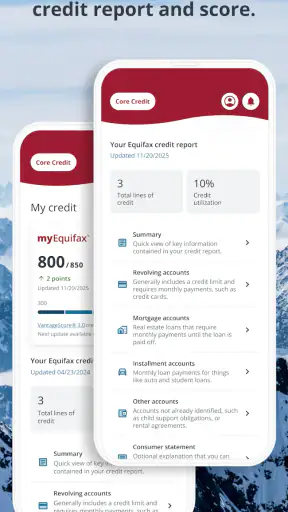
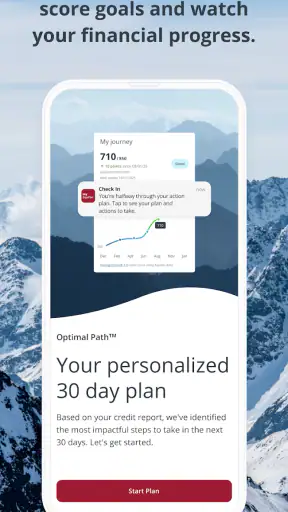
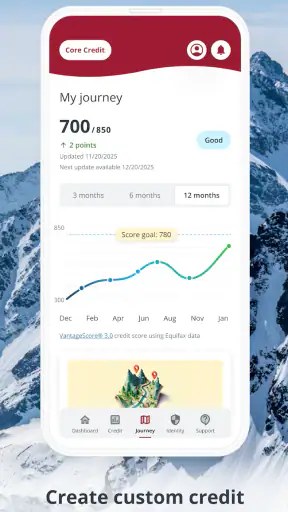
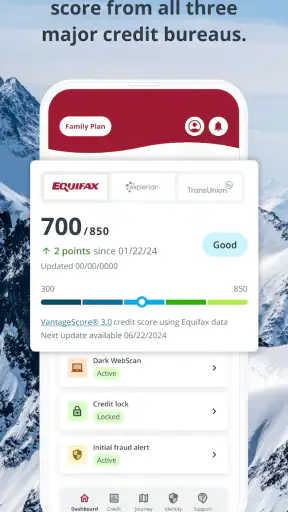
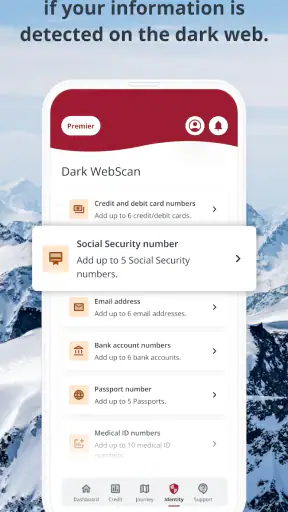
Pros
- Free access to credit scores and Equifax credit report details.
- Credit monitoring alerts can help detect suspicious changes quickly.
- Dispute options make it easier to report inaccurate credit information.
- Identity protection tools provide useful security guidance and resources.
- Clean interface makes key account and credit information easy to find.
Cons
- Some features require a paid Equifax subscription or additional enrollment.
- Credit updates may not appear immediately after financial activity.
- Account verification can be lengthy and may require sensitive information.
- Availability of features can vary by country and account type.
- The app may send frequent promotional messages about Equifax services.
myEquifax - Description
- App Name
- myEquifax
- Package Name
- com.equifax.myequifax
- Developer
- Equifax Incorporated
- Category
- Finance
- Last Updated
- Apr 25, 2025
- Version
- 1.11.0
Managing credit is rarely a one-person task in a household. One person may handle a mortgage application, another may watch for changes before applying for a card, and both may need a clear view of their own financial position. I found myEquifax most useful in that kind of situation: not as a shared family dashboard, but as a personal credit companion that each adult can use separately on a phone.
The app comes from Equifax Incorporated and sits in the finance category. It is free to use, carries an Everyone age rating, and its store summary describes it as a way to start your credit journey. That description is brief, but the practical point is clearer after using it: this is an official place to engage with Equifax-related credit information rather than relying on a random budgeting tool or an unfamiliar third-party service.
I would recommend it to someone who wants a direct starting point and prefers checking credit matters from a mobile device. I would not present it as a complete household finance system, however. It does not replace a shared budget, a conversation about upcoming applications, or the careful handling of each person’s private account. Its value comes from giving an individual a more convenient way to stay involved with their own credit life.
How myEquifax fits into a shared household
Useful when two people need separate visibility
A realistic example is a couple preparing to rent a new home. One partner opens the app to review their own credit situation before submitting an application, while the other checks their own account independently. The important boundary is that the app should be treated as an individual workspace, not as a place where one login casually becomes the household’s shared record.
That distinction matters because credit information is personal. Even when two people share bills, a home, or a device, they do not automatically share the same credit file or the same reasons for checking it. I found the strongest household workflow to be simple: each adult uses their own credentials, checks at a convenient time, and discusses only the information they actually need to coordinate.
This makes myEquifax a better fit for personal credit monitoring habits than for family administration. If your main goal is to divide grocery spending, track subscriptions, or maintain a joint savings target, a budgeting app will usually be more suitable. If your goal is to help each adult pay attention to their own Equifax relationship, this app has a more focused role.
What to do on a shared phone or tablet
Households sometimes use one tablet or pass a phone between family members. In that setting, I would avoid treating the app like a communal utility. Signing out before another person uses the device, keeping the device protected, and avoiding saved credentials are sensible habits for any financial application. They are especially important here because a quick glance at a credit account can reveal information that another household member does not need to see.
I also would not hand the device to a child simply because the app has an Everyone age rating. That rating makes the app broadly suitable from a store-content perspective; it does not mean a child should manage an adult credit account. The account holder should remain the person responsible for signing in, interpreting information, and deciding what action to take.
For shared devices, the practical advantage is convenience, but the trade-off is privacy discipline. A dedicated personal phone is easier to manage. If a shared tablet is the only option, I would make account boundaries part of the routine rather than assuming the app itself will organize the household for me.
Setup boundaries that prevent confusion
My first recommendation is to decide whose account is being accessed before opening the app. That sounds obvious, but it prevents a common household mistake: one person begins a task, another continues it, and nobody is completely sure which account is active. Financial apps reward a slower setup than social apps do.
Use the account holder’s own details and keep the sign-in process personal. Do not create a household convention where one partner stores both people’s access information in a notes app or sends it through ordinary messages. If one person needs help, the safer approach is to sit together while the account holder completes the sensitive steps themselves.
Another useful boundary is to separate observation from action. Checking credit information can be a private review. Applying for a product, disputing an unfamiliar item, or changing account-related details may have consequences that deserve a deliberate conversation. The app can be part of that process, but it should not turn a shared decision into an impulsive tap made by whoever happens to hold the phone.
I also suggest deciding how often each person wants to check in. Checking repeatedly can create anxiety without improving decision-making. A calmer routine is to look when preparing for a meaningful financial step, after noticing something unusual, or during a planned monthly money review. The exact rhythm should fit the person, but it should be intentional rather than driven by worry.
Starting a credit journey without overreading the screen
The app is approachable for someone who is new to credit, but beginners should resist treating every displayed detail as a final verdict on their financial future. Credit information is one input into a lender’s decision, not a promise of approval. A person may use myEquifax to become familiar with their position, then compare that understanding with the requirements of the product they are considering.
This is one of the places where I think the app’s focused identity helps. Instead of opening a broad financial dashboard filled with investments, bills, spending categories, and alerts, a new user can concentrate on credit. The downside is that the app will not provide the full context of a household’s cash flow. Someone who is financially organized in one area can still need a separate tool for the rest.
For a first-time user, I would read slowly, note anything unfamiliar, and avoid making a major application decision from a single glance. If a partner is involved, share the conclusion rather than automatically sharing every private detail. “I checked my credit before we apply” may be all the coordination needed.
Coordinating before a major application
One of the more useful household workflows is a short pre-application check. Each person can review their own information, identify questions, and then discuss timing. This is more practical than discovering at the last minute that one person has an issue they did not understand or that both partners made assumptions about who would apply first.
MyEquifax can support that conversation, but it cannot replace it. The app does not become a shared decision-maker simply because two people use it. I would keep a written list of questions separately and use the app to inform the discussion, not to store a couple’s entire financial plan inside one person’s account.
There is also a timing trade-off. A quick check may be useful before a rental or credit application, but rushing through unfamiliar information can lead to unnecessary panic. If something looks wrong, pause and verify the details through the appropriate Equifax process rather than immediately assuming fraud or blaming a household member. That measured response is a genuine advantage of using a dedicated credit app: it encourages you to inspect the credit side of the decision before acting.
Where it differs from everyday alternatives
Compared with a bank’s mobile app, myEquifax has a narrower purpose. A banking app is usually where I look at balances, transactions, transfers, and payments. It is convenient for managing money already moving through an account, but it is not necessarily the best place to focus on the Equifax side of credit. The choice depends on the question I am asking: “What happened to my checking balance?” points toward the bank, while “What should I understand about my credit position?” points toward myEquifax.
Compared with a general budgeting app, the difference is even clearer. Budgeting tools help households coordinate spending and goals, often with categories and shared planning. myEquifax is not a substitute for that kind of overview. Its advantage is specialization, while its limitation is that it does not give me a complete picture of whether the household can comfortably afford a new obligation.
Compared with checking credit only when a lender asks for it, the app encourages earlier awareness. That can be valuable because surprises are easier to handle before a deadline. Still, someone who rarely needs credit and already has a reliable way to review their information may not need another app on their phone. The convenience is meaningful only if it leads to better attention, not more clutter.
Age, trust, and account responsibility
The Everyone rating may make the app feel approachable for a broad audience, but the financial responsibility remains with the account holder. I would be comfortable explaining the general purpose of the app to a teenager or younger family member, yet I would not let that become an invitation to explore another person’s account. Education and access are different things.
For older relatives, the app may be helpful if they are comfortable using a smartphone, but support should focus on navigation rather than taking control of the account. Sit beside them, let them enter their own sensitive information, and explain what they are viewing in plain language. Trust is easier to preserve when assistance does not quietly become account ownership.
This is also why I would avoid installing it on a device that many people unlock without any privacy controls. The app’s usefulness depends on confidence that the person viewing the screen is the intended account holder. A household can be close and still need firm financial boundaries.
Version, availability, and everyday practicality
The current version is 1.11.0, and the app supports Android 8.0 or later. That makes it practical for people who keep an older Android phone rather than replacing devices frequently. Before relying on it for an urgent financial task, I would still install it in advance and make sure the device can run the current release comfortably.
Its free price lowers the barrier to trying it, especially for someone who is only beginning to pay attention to credit. Free does not mean the app should be approached casually, though. The information involved is more sensitive than the price suggests, so I would use the same care with passwords, device access, and account recovery that I use with other financial services.
The app has an average rating of 4.6 from around 11 thousand ratings, which suggests that many users find the experience worthwhile. I treat that as a useful signal rather than a guarantee. A positive rating cannot tell me whether the app matches a particular household’s needs, especially if that household wants joint budgeting, multiple financial institutions in one view, or extensive planning tools.
Small habits that make the app more useful
My first practical tip is to open the app with a question in mind. For example, I might be preparing for a rental application, checking after receiving an unexpected notice, or learning how credit information is organized. A defined purpose keeps the session focused and makes it easier to decide what needs follow-up.
My second tip is to keep a separate, non-sensitive checklist of questions. If I see a name, account, or entry I do not recognize, I can record a brief reminder without copying private account details into an unsecured note. That helps me investigate calmly while reducing the chance that sensitive information spreads across the household’s devices.
My third tip is to make coordination verbal and minimal. Each partner can say whether they are ready to apply, whether they found something worth investigating, or whether they need more time. There is no advantage in turning one person’s private credit review into a full household data exchange.
A fourth useful habit is to compare credit awareness with affordability. Before taking action, I would look separately at income, existing payments, emergency savings, and the household’s upcoming commitments. myEquifax can help answer one part of the decision, but a strong credit position does not automatically make a new payment comfortable.
Who should use it, and who should skip it?
I think myEquifax is a good match for adults who want a direct, mobile way to begin or maintain a relationship with Equifax. It is especially sensible for someone preparing for a meaningful credit-related step, someone who wants to become more familiar with their own information, or a couple coordinating an application while keeping each person’s account separate.
I would be less enthusiastic for a household seeking a single shared financial command center. If your priority is joint spending, bill assignment, savings targets, or a combined view of several banks, a budgeting or banking alternative will serve you better. The same is true for someone who dislikes managing multiple accounts and has no immediate reason to check their credit.
I would also skip casual shared-login use. Even if it seems convenient, it creates avoidable confusion about whose information is being viewed and who is responsible for the next action. The app works best when its boundaries are respected: one person, one account, one deliberate review.
My household verdict
After using it as a credit-focused finance app, I see myEquifax as a useful specialist rather than a complete household solution. Its free access, straightforward purpose, and mobile format make it an easy starting point for someone who wants to pay attention to credit without first adopting a large financial-planning system. The support for Android 8.0 or later also makes it realistic for users with older devices.
Its main limitation is the same thing that gives it value: the focus is personal credit, not shared money management. Families and couples need to supply the coordination themselves. Each adult should maintain their own account boundaries, discuss decisions before acting, and use a separate tool if they need household budgeting or a complete financial overview.
My final recommendation is simple: install it when you want a clear, individual place to start your credit journey, especially before a significant application or during a period when you are becoming more financially organized. Keep expectations realistic, protect the account on shared devices, and treat the app as one part of a larger decision. For household use, the best approach is separate access with thoughtful coordination, not one shared login pretending to represent everyone.
FAQ
What is myEquifax, and what can I use it for?
myEquifax is Equifax’s mobile and online service for managing credit-related information. After signing in, users may be able to review their Equifax credit report, monitor changes, receive alerts, access identity-protection features, and explore available credit or financial tools. The exact features depend on your country, account type, subscription, and eligibility, so the app should be viewed as a monitoring and information service rather than a complete financial-management platform.
Is myEquifax free to download and use?
Downloading myEquifax is generally free, but not every feature is necessarily included at no cost. Some services, such as enhanced credit monitoring, identity theft protection, additional reports, or premium support, may require a paid plan or may only be available through a qualifying Equifax product. Before activating a trial or subscription, carefully review the pricing, renewal terms, cancellation policy, and whether charges apply after the introductory period.
How secure is my personal information in myEquifax?
Because myEquifax handles highly sensitive information, including identity and credit data, the service uses account-security measures such as password protection, verification steps, encrypted connections, and security alerts. However, no online service is completely risk-free. Use a unique password, enable available multi-factor authentication, keep your phone updated, avoid signing in through public Wi-Fi, and contact Equifax immediately if you notice unfamiliar activity or changes to your account.
Can I get my credit score and credit report through myEquifax?
myEquifax may provide access to an Equifax credit report, credit score, or report-monitoring tools, but availability varies by location and membership. A score shown in the app may use a particular scoring model and may not match the score used by a lender, insurer, or card provider. Checking your own report through the service generally does not harm your credit score, although applications for credit can involve separate hard inquiries.
What should I do if I find an error or suspicious activity in myEquifax?
If your report contains inaccurate information, use the dispute process provided by Equifax and submit clear supporting documentation when requested. For suspected identity theft, unauthorized account changes, or unfamiliar inquiries, secure your myEquifax account immediately, change your password, review security settings, and contact Equifax through its official support channels. You may also need to contact the relevant creditor and follow local identity-theft reporting guidance.


